
On 23rd June 2026, HMRC published a consultation called “Modernising the taxation of distributions and repayments of capital from companies”. It covers demergers, share buybacks (purchase of own shares), dividends, loans to participators and the "transactions in securities" anti-avoidance rules.
The aim of this is quite simple. HMRC wants to stop owners taking value out of a business they keep running and paying capital gains tax on it, when it thinks income tax should apply.
What is a demerger and why is it used before a sale?
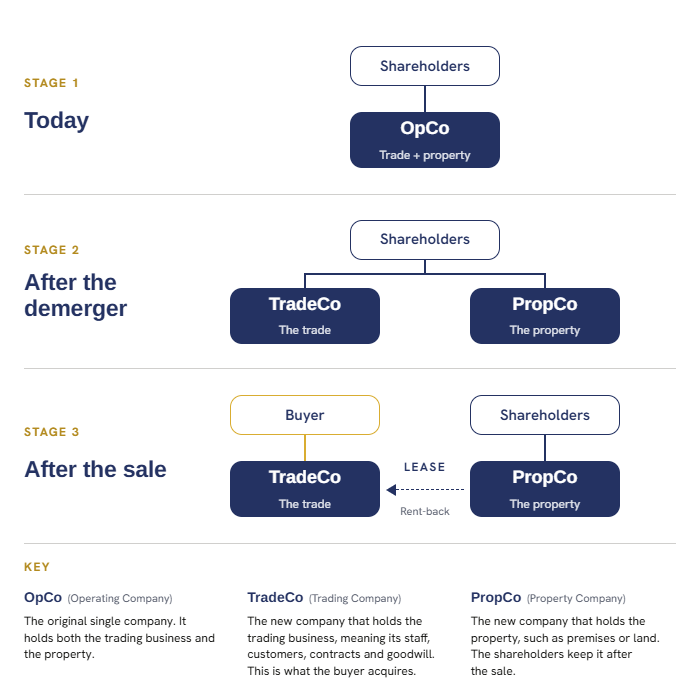
A demerger splits one company into two or more separate companies that stay with the same shareholders.
The typical case before a sale is a trading company that owns its premises. Essentially, the buyer wants the trade but not the property. The owners want to keep the property, perhaps to rent it back to the buyer or to hold it as a long-term investment. A demerger puts the trade and the property into separate companies, so the trade can be sold and the property kept.
At the moment, this is often done through a "capital reduction" demerger. When it’s done properly, and with correct HMRC clearance, it normally creates no immediate tax charge.
What might be changing?
The capital reduction route could effectively end
HMRC is proposing to remove the tax mechanism that currently makes the conventional capital reduction demerger work. Importantly, though, this is not yet legislation. The consultation closed on 14 September 2026, and as at 6 October 2026 the government has not yet published its response or draft legislation.
Statutory demergers could become the main route (with a five-year condition)
HMRC plans to relax several demerger conditions. For example, demergers of investment activities would be allowed. However, a statutory demerger could not be used to facilitate a sale, change of control, or ceasing trade within five years.
Could you still split property and trade just before selling?
Under the new proposals, you could split property and trade before a sale, but not without a significant tax cost.
If you were to take a trading company worth £2m that owns a £1m worth of property. Today, the two can usually be separated shortly before a sale with no immediate tax. Under the proposed rules, the capital reduction route would generate an “income distribution”.
The statutory route would not be available either, because a sale is planned within five years.
For an additional-rate taxpayer, dividends are taxed at 39.35%. A distribution of £1m could therefore mean a personal tax bill approaching £400,000 on a restructuring that currently costs nothing in tax.
~£400,000 figure is illustrative only. It applies the 39.35% additional dividend rate to £1m and ignores reliefs and any other taxes.
When might the changes take effect?
We don’t yet know when these changes might take effect because this is just a consultation, not draft legislation yet. These changes could be announced in the 2026 Autumn Budget. They could also appear in a later Finance Bill in revised form, or they might be scrapped completely!
Once HMRC has signalled its intention, whether it is confirmed or not, business owners can no longer assume that today's options will still be there when they're ready to sell later on.
What should I do if I'm planning to sell in the next few years?
There is no one-size-fits-all plan that will suit every business owner and their plans; however, the following tips are generally applicable to most, and are therefore worth considering properly as early as possible in your planning.
- Review your structure. Does your company hold property, investments or a second business that a buyer is unlikely to want?
- If a demerger is already planned or under way, discuss with your advisers whether to complete it while the current rules apply.
- Plan around five years. If the statutory demerger route becomes the only tax-efficient option, the split may need to happen well before any sale.
- Get the clearance right first time. HMRC also proposes removing the automatic right of appeal to the Tribunal on clearance decisions.
- Bring your corporate finance and tax advisers together early, so the deal timetable and the tax structure support each other.
Pre-sale restructuring has often been done in the final months before a deal. If these proposals go ahead, that approach could turn a tax-neutral step into a six-figure income tax bill. Whatever the final rules look like, owners who plan ahead will have more options and pay less tax than those who wait.
This article is for general information only and does not constitute tax advice. The proposals are subject to consultation and may change. Always take professional advice before restructuring.